
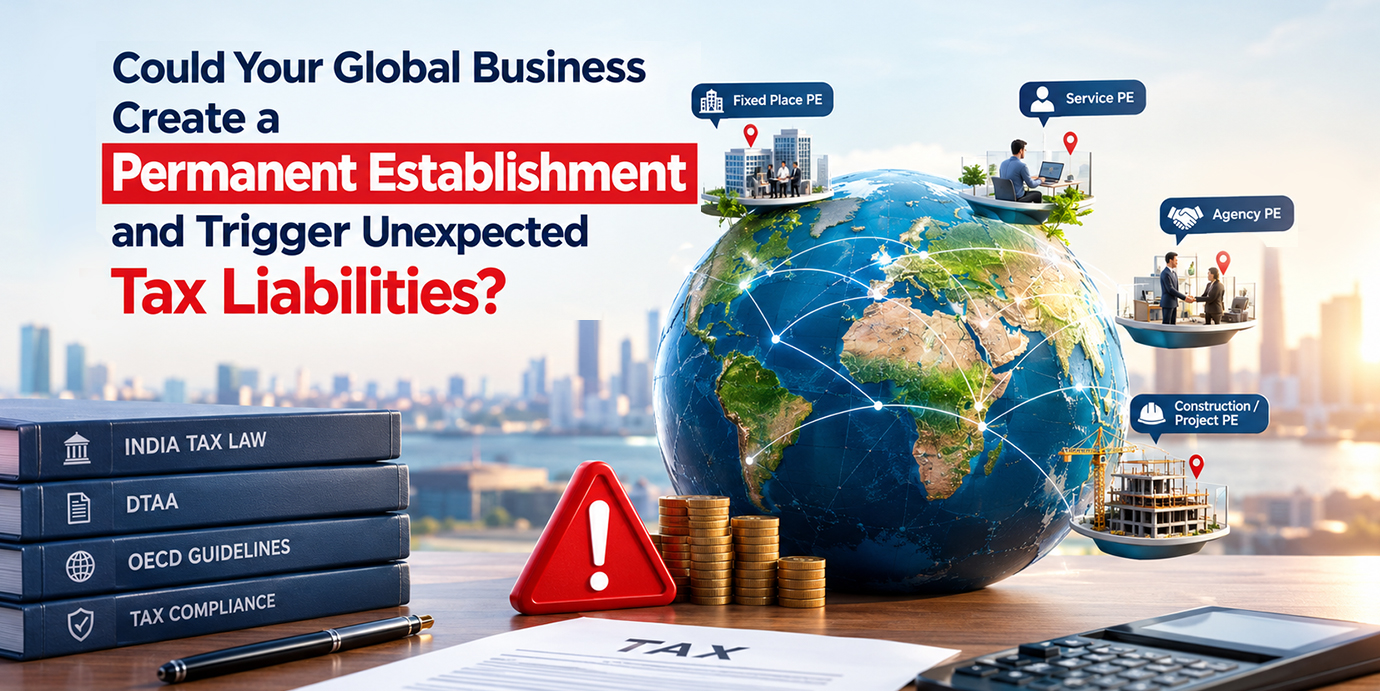
When Business Without Borders Creates Tax Exposure
In today’s interconnected business environment, companies can access international markets without establishing a physical office in every country where they operate. A foreign enterprise may serve Indian customers remotely, deploy employees to India, engage local representatives, or provide consulting and technical services across borders. However, an important question arises: Can a company become liable to pay tax in another country even if it has not incorporated a subsidiary or established a formal branch there?
The answer is yes. Depending on the nature of its activities and the provisions of the applicable tax treaty, a foreign enterprise may create a taxable presence in another country without establishing a separate legal entity. This is where the concept of Permanent Establishment (PE) becomes critical. For multinational enterprises, foreign investors, technology companies, and businesses expanding internationally, understanding PE is essential to managing tax exposure, ensuring compliance, and avoiding unexpected tax disputes.
What Is a Permanent Establishment?
A Permanent Establishment generally refers to a business presence that enables a country to tax the profits attributable to a foreign enterprise’s activities within its territory.
Article 5 of many Double Taxation Avoidance Agreements (DTAAs) defines a PE as a fixed place of business through which the business of an enterprise is wholly or partly carried on.
However, the precise definition varies across tax treaties. Some treaties contain additional provisions relating to service activities, construction projects, dependent agents and other circumstances that may establish a taxable presence. The underlying principle is that a country may acquire the right to tax a foreign enterprise’s business profits when its activities satisfy the relevant PE conditions under the applicable treaty.
For example, a company headquartered in the United States may provide services to Indian customers. If its activities in India satisfy the relevant PE provisions, India may be entitled to tax the profits attributable to that PE, subject to the applicable treaty and domestic tax law. Importantly, having customers in a country does not automatically create a PE. The nature, duration, and substance of the enterprise’s activities must be examined in light of the applicable legal provisions.
What Are the Different Types of Permanent Establishment?
PE exposure can arise in several ways, depending on the enterprise’s business activities and the provisions of the applicable tax treaty. The principal categories include the following.
A. Fixed Place PE
A Fixed Place PE may arise when a foreign enterprise carries on its business through a sufficiently permanent place of business in another country and the relevant treaty conditions are satisfied.
Common examples include:
- A branch or office through which business operations are conducted.
- A factory or workshop.
- A place of management.
- Other premises used to carry on the enterprise’s business, where the applicable conditions are met.
The assessment generally considers whether a place of business exists, whether it has the requisite degree of permanence, whether it is at the enterprise’s disposal, and whether is the enterprise carries on business through that location. The mere existence of a subsidiary in another country does not, by itself, establish a PE of its foreign parent. The actual arrangements, the relationship between the entities, and the activities performed must be evaluated.
B. Service PE
Certain tax treaties contain specific Service PE provisions. These may apply when a foreign enterprise furnishes services in another country through employees or other personnel for a specified period.
The applicable threshold varies by treaty. It may depend on the number of days for which services are performed, the nature of the services, or to the duration of a particular project.
For instance, an overseas consulting firm deploying personnel to India for an extended client engagement should examine whether the applicable India treaty contains a Service PE provision and whether the prescribed conditions are satisfied.
There is no universal rule under which a particular number of days automatically creates a Service PE in every country. The relevant treaty provisions must be examined before drawing a conclusion.
C. Agency PE
A foreign enterprise may create an Agency PE when a person acting on its behalf in another country satisfies the relevant treaty conditions.
This risk may arise when a local representative habitually concludes contracts, or plays the principal role leading to contracts that are routinely concluded without material modification, depending on the wording of the applicable treaty.
Businesses should therefore assess not only their formal contractual arrangements but also the actual authority, responsibilities, and commercial functions exercised by their local representatives. An independent agent acting in the ordinary course of business may qualify for an exception under treaties, subject to the applicable conditions.
D. Construction or Project PE
Construction, installation, and supervisory projects may trigger a PE when they continue beyond the duration threshold specified in the relevant tax treaty.
For example, an overseas engineering company executing an installation project in India must examine the applicable treaty’s duration test, including any provisions governing connected projects and supervisory activities.
Project timelines, personnel deployment, and contractual arrangements can therefore have significant tax implications. Businesses should assess these factors before commencing a project and monitor them throughout its execution.
Can Remote Working Create a Permanent Establishment?
Remote working has introduced an additional dimension to PE analysis, particularly for multinational enterprises with employees working across borders.
Consider a foreign company whose employee works from India for an extended period while performing responsibilities connected with the company’s overseas business. Could the employee’s home constitute a Fixed Place PE?
The answer depends on the facts and the provisions of the applicable tax treaty.
Relevant considerations may include:
- Whether the home or other location is effectively available to the enterprise as a place of business.
- Whether the arrangement is temporary or forms part of a regular working pattern.
- Whether the employee’s presence in India serves a commercial purpose for the enterprise.
- Whether the activities performed from that location form a substantive part of the enterprise’s business.
The OECD’s 2025 update to its Model Tax Convention commentary provides further guidance on when cross-border working from a home or another location may, or may not, create a Fixed Place PE. These developments are particularly relevant to multinational groups employing personnel across borders. However, OECD commentary must be considered in the context of the applicable treaty, its wording, and the relevant interpretative framework.
Businesses should not assume that every employee working remotely creates a PE. Equally, they should not assume that the absence of a leased office automatically eliminates the risk.
Permanent Establishment in India and What Foreign Companies Should Know
For foreign enterprises operating in India, PE analysis requires consideration of both domestic tax law and the applicable DTAA.
Indian income-tax law contains provisions governing income deemed to accrue or arise in India, including income attributable to a business connection in India. Tax treaties may separately restrict India’s right to tax business profits unless the relevant PE or other treaty conditions are satisfied.
Where a foreign enterprise is eligible for treaty benefits, the interaction between domestic law and the applicable treaty must be evaluated in accordance with the governing legal provisions.
A finding that a PE exists does not mean that all the foreign enterprise’s global profits become taxable in India. Generally, the focus is on determining the business profits attributable to the Indian PE under the applicable rules.
This attribution exercise may require analysis of the functions performed, assets employed, risks assumed, and dealings between the Indian operations and the overseas enterprise.
It is also important to distinguish PE taxation from other Indian tax obligations. Payments to non-residents may require separate analysis under provisions relating to royalties, fees for technical services, withholding tax, and other applicable rules. The absence of a PE does not automatically eliminate every potential Indian tax liability.
What Are the Consequences of Creating a PE?
An unexpected PE determination can have consequences extending beyond the immediate tax cost.
Income-tax exposure: Profits attributable to the PE may become taxable in the country concerned, subject to the applicable domestic law and treaty provisions.
Compliance obligations: Depending on the circumstances, registration, tax return filing, maintenance of accounting records, and other compliance requirements may arise.
Interest, penalties and disputes: Failure to identify a taxable presence in time may result in tax assessments, interest, applicable penalties, and prolonged disputes or litigation.
Transfer pricing considerations: Transactions between associated enterprises may require separate transfer pricing analysis, documentation and compliance, where applicable.
Commercial uncertainty: An unresolved PE position can affect project pricing, customer contracts, internal budgets, and decisions concerning future market expansion.
These risks reinforce the importance of assessing PE exposure before commencing or materially changing cross-border operations.
How Can Businesses Manage Permanent Establishment Risks?
PE risk management should be integrated into international expansion and day-to-day operating decisions rather than treated solely as a year-end tax exercise.
Businesses should consider the following measures:
1. Review the applicable tax treaty: Identify the specific provisions governing Fixed Place, Service, Agency, and Project PE, including relevant exceptions and duration thresholds.
2. Map cross-border activities: Track employee travel, project timelines, local decision-making, contract negotiations and the functions performed in each jurisdiction.
3. Examine contractual and operational arrangements: Ensure that agreements accurately reflect how the business operates in practice. Contractual labels alone do not determine the tax outcome.
4. Assess remote-working arrangements: Establish a process to review cross-border employee locations, their responsibilities, and the business reasons for their presence.
5. Maintain supporting documentation: Retain travel records, contracts, project reports, authority matrices, correspondence, and other evidence relevant to the PE assessment.
6. Review profit attribution and compliance: Where a PE exists or is reasonably likely to exist, evaluate the appropriate profit attribution methodology, tax filings, and related compliance obligations.
7. Reassess periodically: Business models evolve. New contracts, expanded employee responsibilities, changes in project duration, or revised operating arrangements can alter the PE position.
International Growth Requires More Than a Commercial Strategy
Expanding into international markets presents significant opportunities, but it also introduces complex tax considerations. A company may establish a taxable presence through its operational arrangements even without setting up a formal subsidiary or branch.
Permanent Establishment analysis is therefore not merely a technical tax exercise. It is an important component of international business planning, risk management, and regulatory compliance.
For foreign enterprises entering India and Indian businesses expanding overseas, a structured PE assessment can help identify potential exposure early, support informed commercial decisions and reduce the risk of avoidable tax disputes.