
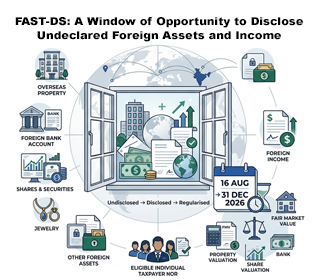
As announced in the Union Budget 2026, CBDT has notified the Foreign Assets of Small Taxpayers – Disclosure Scheme (FAST – DS), effective from 16th August 2026 to 31st December 2026. FAQs have also been issued to provide further clarity on the scheme. FAST-DS presents a valuable opportunity for small taxpayers to voluntarily disclose foreign assets or income that may have been inadvertently omitted from their Income Tax Returns, including foreign bank accounts, overseas investments, ESOPs/RSUs, insurance policies and other foreign assets.
A Non-Resident (NR) or Resident but Not Ordinarily Resident (RNOR) can make a declaration under the scheme if he was resident in India in the year to which the undisclosed income relates or in the year in which the undisclosed asset was acquired.
FAST-DS Broadly Covers Two Categories:
1. Undisclosed foreign income or undisclosed foreign assets, where the prescribed aggregate fair market value does not exceed Rs.1 crore.
The amount payable under this category is the aggregate of
i. Tax at 30% of the value of the asset located outside India as on 31st March 2026;
ii. Tax at 30% of the undisclosed foreign income;
iii. 100% of the amount calculated under (i) and (ii).
Undisclosed Foreign Asset means an asset, including a financial interest in any entity, located outside India and held by the assessee in his own name or in respect of which he is the beneficial owner, where he has no explanation about the source of investment, or where the explanation provided is, in the opinion of the Assessing Officer, unsatisfactory.
Undisclosed Foreign Income means the total amount of income of an assessee from a source located outside India that was chargeable to tax in India but has not been offered to tax.
The monetary threshold under this category is that the aggregate value of the undisclosed assets located outside India as on 31st March 2026 and the undisclosed foreign income must not exceed ₹1 crore.
2. Assets located outside India acquired from income accruing or arising outside India while being a non-resident and not declared on becoming a resident; or assets located outside India acquired from income offered to tax in India but not declared, where the aggregate value of such assets does not exceed ₹5 crore.
The amount payable under this category is fee of ₹1 lakh.
The monetary threshold under this category is that the value of the qualifying assets under Category B must not exceed ₹5 crore. This category provides relief in cases where the source of the asset is not undisclosed income, but the foreign asset itself was not appropriately reported or disclosed.
The valuation date prescribed under the scheme is 31 March 2026. As a general rule, the Fair Market Value (FMV) is the higher of (a) the cost of acquisition, and (b) the price the asset would ordinarily fetch if sold in the open market on the valuation date. Ideally, the valuation should be supported by a report from a valuer recognised by the government or its agency in the country where the asset is located.
Where such market valuation is not carried out, the indexed cost of acquisition is deemed to be the Fair Market Value. The FAQs issued for the scheme provide specific methods for determining the FMV of various categories of assets, including bullion, jewelry or precious stones, archaeological collections, paintings, sculptures or other artistic works, quoted shares and securities, unquoted equity shares, unquoted shares/securities other than equity shares, immovable property located outside India, foreign bank accounts, and other assets.
With a defined time, window and specific valuation and payment mechanisms, FAST-DS provides taxpayers an opportunity to regularise certain previously undisclosed foreign assets and income. Taxpayers with overseas holdings or income that may not have been appropriately reported should evaluate their position carefully and determine whether they qualify for the scheme before the 31 December 2026 deadline.