
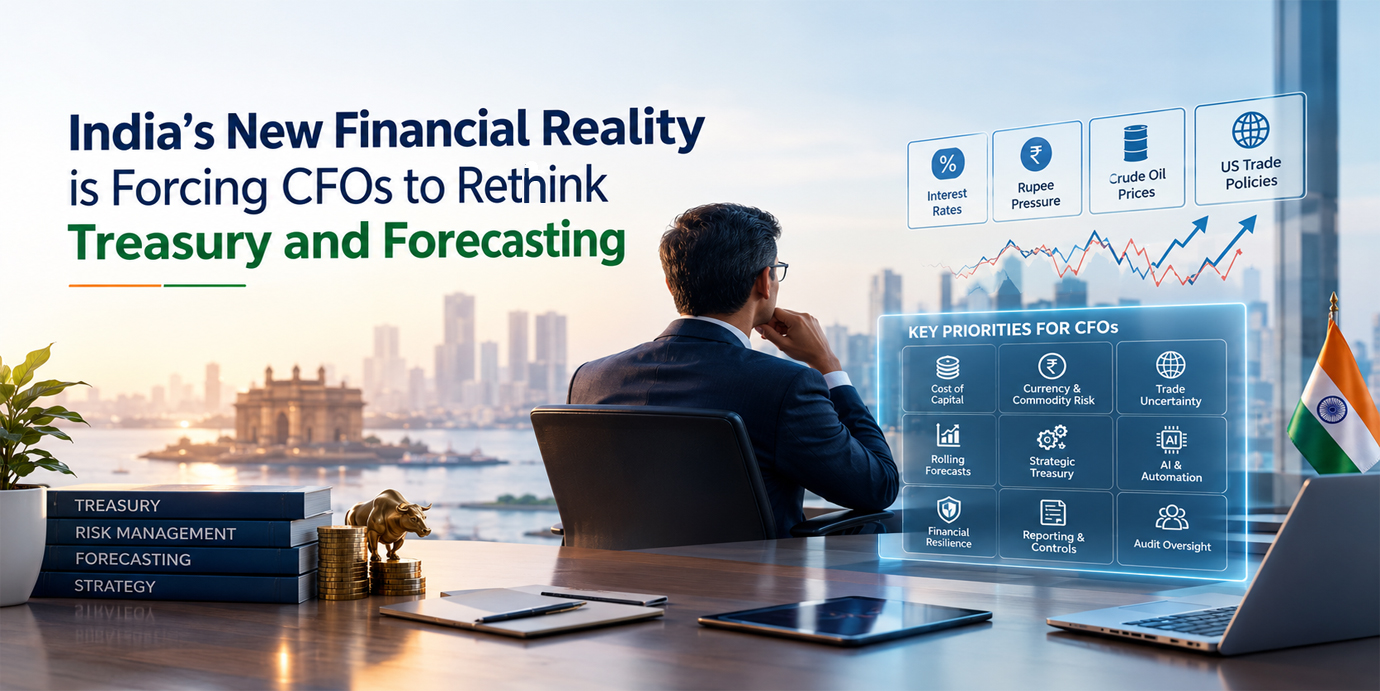
Finance & Accounting Insights | October 2026 | India Edition
The annual budget was built for a world that no longer exists.
For much of the past two years, Indian finance teams operated on a relatively comfortable assumption: inflation was moderating, the Reserve Bank of India (RBI) was easing monetary policy, and the rupee’s depreciation remained manageable. That assumption has now been challenged. On 7 October 2026, the RBI raised the policy repo rate by 25 basis points to 5.50% and shifted its monetary policy stance to calibrated tightening. Meanwhile, the rupee remains under pressure, crude oil prices continue to influence India’s import bill, and US trade measures are adding uncertainty to the export outlook.
For CFOs, these developments are more than macroeconomic headlines. They directly affect borrowing costs, operating margins, working capital, capital allocations, and financial forecasts. This article examines what has changed for Indian businesses, how these developments affect the profit & loss account and balance sheet, and the practical steps CFOs can take to turn volatility into a competitive advantage.
The Macro Backdrop – The RBI Pivots from Easing to Tightening
The RBI’s Monetary Policy Committee (MPC) voted unanimously on 7 October to raise the repo rate by 25 basis points, from 5.25% to 5.50%. The Standing Deposit Facility rate increased to 5.25%, while the Marginal Standing Facility rate and Bank Rate to 5.75%. The decision marked the RBI’s first-rate hike since February 2023 and signaled a shift towards tighter monetary conditions. Near-term rate cuts have consequently become less likely.
The shift reflects a more challenging inflation outlook. The RBI revised its FY27 CPI inflation projection upwards to 5.2% from 5.0%, citing weather-related disruptions, El Niño risks, and volatile oil prices. Its quarterly projections indicate inflation of 4.9% in Q2, 6.0% in Q3, 5.7% in Q4, and 5.6% in Q1 of FY28. Growth, however, remains resilient. The RBI raised its FY27 real GDP growth forecast to 7.1% from 6.7%, supported by domestic demand and investment.
Financial markets respond quickly. Government bond yields moved higher, short-term borrowing costs came under pressure, and currency markets remained volatile. These developments reinforce the possibility of tighter financing conditions for businesses, even as the broader economy continues to expand.
The impact: CFOs who built their budgets around stable or declining interest rates need to revisit their assumptions. Borrowing costs, discount rates, customer financing conditions, and demand in rate-sensitive sectors must be reassessed before the next board review.
1. Cost of Capital Is Now a Strategic Variable
In India, changes in the repo rate can affect borrowing costs relatively quickly, particularly where loans are linked to external benchmarks. Floating-rate working-capital facilities and term loans reprice as benchmark rates change, putting immediate pressure on interest expenses and cash flows.
CFOs should respond in four key areas.
• Re-underwriting hurdle rates. Capital expenditure committees should reassess proposed investments against a higher cost of capital. Projects should be ranked on payback periods, cash conversion, return on invested capital, and downside resilience rather than growth potential alone.
• Reviewing the debt mix. Floating-rate exposure, loan tenor, and refinancing schedules should be mapped against possible further rate increases. Fixed-rate borrowing or interest-rate protection may be worth considering where the economics and risk profile justify it.
• Stress-testing covenants. Interest coverage, leverage ratios, and debt-service capacity should be modelled quarterly under multiple interest-rate scenarios. When covenant headroom is limited, early discussions with lenders can help avoid last-minute financing pressure.
• Rebuilding M&A and expansion cases. Acquisitions and greenfield investments that depended on inexpensive debt should be reassessed using realistic financing assumptions, operational synergies, and working-capital improvements.
The impact: Higher financing costs flow directly into profit after tax and free cash flow. For leveraged sectors such as real estate, infrastructure, and NBFC-funded consumer businesses, a poorly timed refinancing or an unexpected increase in interest expense can quickly erode operating gains.
2. The Rupee, Oil, and the Import Bill
India’s external position presents another challenge for finance leaders. A weaker rupee raises the domestic cost of imported goods, raw materials, energy, and foreign-currency debt servicing. Elevated crude oil prices can compound this pressure because India relies heavily on imported crude to meet its energy needs. Together, currency depreciation and higher oil prices can widen the import bill, put pressure on the balance of payments, and contribute to domestic inflation.
The relationship between currency movements and monetary policy makes the situation more complex. A weaker rupee can increase imported inflation, potentially influencing the RBI’s future policy decisions. Currency, crude oil, and rates should therefore be treated as interconnected risks rather than separate forecasting variables.
CFOs in import-intensive industries, including manufacturing, aviation, chemicals, and consumer goods, should focus on four priorities:
• Building rupee and crude scenario bands. Forecasts should incorporate multiple exchange-rate and commodity-price assumptions rather than rely on a single budget rate.
• Reviewing hedge ratios and tenors. Dollar payables, external commercial borrowings, and import contracts should be assessed against forecast certainty, hedge costs, and the timing of expected cash flows.
• Testing pricing power. Businesses should evaluate their ability to pass higher input costs to customers, including the speed and extent of surcharge or index-linked price adjustments.
• Reducing unhedged foreign-currency exposure. Particular attention should be given to foreign-currency debt and other exposures that could materially increase liabilities if the rupee depreciates further.
The impact: Without timely visibility into currency and input-cost movements, margin erosion may become apparent only when quarterly results are reported, leaving little room to respond. Exporters may benefit from improved rupee realisations, but that advantage depends on overseas demand, tariff treatment, and their exposure to imported inputs.
3. US Trade Measures and the Export Outlook
The United States remains a critical market for Indian exporters, making changes in US trade policy particularly significant. In July 2026, the US announced an additional 10% duty on Indian goods under Section 301 measures associated with its investigation into forced-labour import restrictions covering 60 economies. India and the US continue to navigate broader trade negotiations, leaving businesses exposed to uncertainty over market access and competitiveness. Labour-intensive sectors such as textiles, leather, gems and jewelry, and may be particularly sensitive to changes in duties, customer sourcing decisions, and price competition.
For controllers and financial planning and analysis (FP&A) teams, trade volatility is an accounting and disclosure issue as well as a commercial challenge:
• Revenue and margin visibility. Exporters need customer-level and product-level views of tariff exposure, pricing concessions, rebates, and contribution margins so that deterioration is identified early.
• Inventory and receivables. Slow-moving export inventory may require reassessment of net realisable value under Ind AS 2. Delayed customer payments may also require a review of expected credit losses under Ind AS 109.
• Government support. Export incentives and relief schemes should be incorporated into financial models where relevant, with recognition based on the applicable eligibility and accounting criteria.
• Supply chain redesign. Diversifying export markets, changing sourcing locations, and restructuring supply chains can create new capital expenditure, transfer-pricing, tax, and compliance implications.
• Forward-looking disclosures. Material trade uncertainties should be reflected in management commentary and risk disclosures, where required. Generic statements may not adequately explain the nature or potential financial impact of the risks.
The impact: Exporters without granular customer-level visibility risk losing control of their margins. Those with reliable data can assess pricing options, diversify markets, review available support, and respond faster to changes in trade policy.
4. From Annual Budgets to Driver-Based Rolling Forecasts
When interest rates, currency movements, oil prices, and trade policy can change materially within a quarter, a budget approved in March and left largely untouched for twelve months can quickly become an unreliable decision-making tool. Indian finance teams need to move towards continuous, driver-based planning that connects operational developments with financial outcomes.
Five elements are central to this approach.
1 Driver-based architecture. Link business drivers, including volumes, price realisation, crude and commodity costs, the INR/USD exchange rate, repo-linked interest expenses, and tariff exposure, directly to the profit and loss account, balance sheet, and cash flow.
2 Rolling forecast horizon. Maintain a forward-looking view of 12-to-18-months, refreshed monthly or quarterly, so the management retains a consistent planning horizon throughout the financial year.
3 Parallel scenarios. Run base, downside, and severe-stress scenarios simultaneously. These could include the rupee weakening to ₹100 case per US dollar or a further 50-basis-point increase in policy rates, with the assumptions clearly identified as illustrative stress tests rather than predictions.
4 Pre-agreed triggers. Define the events that prompt management action, such as an MPC decision, an unexpected CPI reading, a crude-price threshold, or a major trade-policy announcement. Link these triggers to specific responses, including pricing changes, hiring pauses, cost controls, or capital expenditure deferrals.
5 Decision-focused reviews. Shift finance discussions from explaining historical variances to deciding what actions are needed, who owns them, and when results should be reviewed.
The impact: Faster forecasting reduces decision latency. When interest rates rise or currency assumptions change, finance teams can update projections, assess liquidity implications, and recommend corrective action before outdated assumptions affect business performance.
5. Treasury Moves from Back Office to Command Center
With financing costs rising, currency markets volatile, and liquidity conditions potentially tightening, treasury must operate as a strategic risk-management function rather than a simply payment-processing unit.
Hedge architecture. Static annual hedge ratios can be inadequate when exchange rates and forecast certainty change rapidly. Layered hedging programmes, staggered tenors, and exposure-based hedge ratios can help businesses manage risk more systematically. Decisions should reflect forecast reliability, forward premiums, cash-flow timing, and applicable regulatory policy limits.
Liquidity and cash visibility. Centralised cash management, timely visibility across entities and bank accounts, and disciplined working-capital management can reduce idle cash and unnecessary borrowing. Receivables, inventory, and payment cycles should be monitored closely because excess working capital carries financing cost. For payments to micro and small enterprises, finance teams should also monitor the applicable statutory timelines, including the 45-day maximum where a written payment agreement applies under the MSMED Act, and the related income-tax implications under Section 43B(h).
Funding diversification. A balanced funding mix, including bank facilities, corporate bonds, commercial paper, and other suitable financing options – can reduce dependence on a single source of capital. Treasury teams should maintain maturity ladders, monitor refinancing concentrations, and evaluate issuance windows against prevailing market conditions.
Counterparty and supply chain risk. Financial stress can spread across suppliers, distributors, and customers. Treasury should work with procurement and commercial teams to monitor the financial health of critical counterparties and identify potential disruptions before they affect operations.
The impact: Stronger cash visibility and disciplined hedging can reduce earnings volatility, improve liquidity management, and help CFO answer the board’s most important question: what happens to the business if conditions deteriorate further?
6. AI and Automation: Where the Return on Investment is Real
Artificial Intelligence in finance offers genuine opportunities, but its value depends on whether it improves decision quality, strengthens controls, or reduces the time required to complete routine work. The most credible applications are those that address specific operational bottlenecks:
• Accelerating financial close and reconciliations. Automated matching and exception handling can streamline bank and GST reconciliations, helping finance teams identify discrepancies more quickly.
• Detecting anomalies. Analytical tools can flag unusual journal entries, expense claims, and sub-ledger movements for further investigation.
• Improving cash and demand forecasting. Machine-learning models can use historical patterns and relevant business drivers to support cash-flow projections and rolling forecasts.
• Streamlining variance analysis and commentary. Automation can assist with identifying key movements and preparing initial explanations, allowing analysts to focus on interpretation and recommendations.
Effective governance remains essential. Data qualit, model-risk management, access controls, human review, and auditability should be built into implementation from the outset. AI should support the wider treasury and forecasting agenda rather than become a standalone technology initiative without measurable business outcomes.
The impact: Finance teams can shift away from repetitive data gathering towards analysis, decision support, and strategic business partnering—provided automation delivers measurable efficiency gains without weakening controls.
Controls, Reporting, and the Audit Committee Lens
Greater volatility increases the importance of financial reporting quality and accounting judgement. Audit committees and auditors and auditors should pay particular attention to areas where changing assumptions can materially affect reported results. These include impairment testing under Ind AS 36, foreign-currency translation under Ind AS 21, hedge accounting and financial instrument under Ind AS 109, expected credit losses, inventory valuation, debt classification, covenant compliance, going-concern assessments, and disclosure relating to significant uncertainties.
The practical response is to document material assumptions and sensitivities, maintain consistency between internal forecasts and the assumptions used for accounting estimates where appropriate, and engage auditors early when significant judgement is required. Changes in economic conditions should be reflected in estimates and disclosures in accordance with the applicable accounting standards.
The CFO Agenda: Five Moves to Make Before the December MPC
1 Re-run debt and covenant stress tests. Model borrowing costs and covenant headroom under repo-rate scenarios of 5.75% and 6.00%, and engage lenders early where financial flexibility is limited.
2 Build rupee and crude scenarios into the forecast. Establish clear assumptions and pre-agreed triggers for hedging, pricing changes, and cost-control measures.
3 Establish customer-level trade and duty visibility. Quantify export exposure to US trade measures, assess potential margin impacts, and evaluate available government support.
4 Rebuild the hedging policy around volatility, not averages. Review layered hedge ratios, staggered tenors, forecast confidence, and governance to ensure the policy reflects actual exposures.
5 Replace static budgeting with driver-based rolling forecasts. Maintain a forward-looking planning horizon and deploy automation where it demonstrably improves speed, accuracy, or control.
The Bottom Line
Volatility is no longer an exception to plan around; it is a part of the operating environment. India’s growth outlook remains resilient, with the RBI projecting real GDP growth of 7.1% for FY27. However, rising financing costs, currency pressure, and uncertain trade conditions are making financial decisions more complex.
The finance function’s challenge is to turn that uncertainty into an advantage. CFOs who build agility into treasury, forecasting, capital allocation, and reporting will be better positioned to protect margins, preserve strategic flexibility, and strengthen credibility with boards and investors. Those who continue to rely on outdated assumptions risk making decisions for a world that no longer exists.